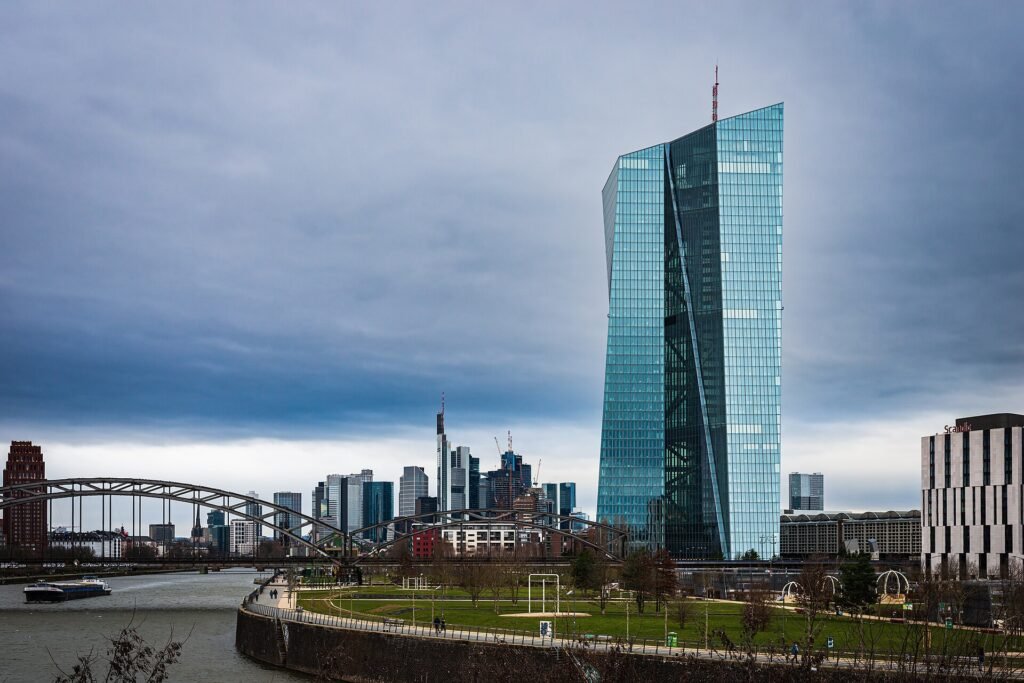
Norbert Nagel · CC BY-SA 4.0 · Wikimedia Commons · Source · License
The European Central Bank (ECB) has unanimously decided to keep its three key policy rates unchanged, despite renewed energy price increases and ongoing inflation uncertainty within the Eurozone. While rising oil and gas costs—exacerbated by escalating Middle East conflicts—have intensified upward pressure on inflation, the decision reflects a judgment that core inflation and wage growth remain on a stable trajectory.
Three Key Policy Rates Held Steady and Interest Rate Framework
The ECB Governing Council held its regular meeting on October 29, 2026, and determined to maintain the three core policy rates for the Eurozone. Consequently, the interest rate on the deposit facility remains at 2.50%, the main refinancing operations rate at 2.65%, and the marginal lending facility rate at 2.90%. The ECB reaffirmed its commitment to maintaining a restrictive monetary policy stance for as long as necessary to ensure that inflation returns to its 2.0% medium-term target.
Analysis of Energy Price Spikes and September Eurozone Inflation Data
The decision to hold rates was largely influenced by the energy price shocks recently triggered by geopolitical risks. According to official data released by the ECB, the headline inflation rate in the Eurozone reached 3.8% in September 2026, a 0.6 percentage point increase from the previous month (3.2%). The energy component was the primary driver, with its inflation rate surging from 14.3% in August to 18.9% in September. High refining margins, coupled with increased prices for gasoline and diesel, were identified as the key factors behind this spike.
Other inflation indicators, excluding energy, generally showed moderate increases or remained stable.
- Inflation excluding energy: 2.3% in September (vs. 2.1% in August)
- Services inflation: 3.2% in September (vs. 3.0% in August)
- Food inflation: 1.3% in September (vs. 1.1% in August)
- Goods inflation: 1.1% in September (a slight decline compared to 1.2% in August)
Wage Growth Stability and Labor Market Trends
Despite energy-driven inflationary pressures, wage growth—a key component of underlying inflation—remained within a controllable and stable range. Compensation per employee grew by 3.3% in the second quarter of 2026, a slowdown from the 3.6% recorded in the first quarter, as gradual gains in labor productivity helped mitigate the rise in unit labor costs. ECB wage tracker analysis suggests that negotiated wage growth for the second half of 2026 will likely fluctuate between 2.5% and 2.8%, before settling at an average of 2.6% throughout the first three quarters of 2027.
The Eurozone labor market remains resilient, with the unemployment rate at a historic low of 6.4% in August 2026. Business sentiment in the services sector has recovered from the initial weakness caused by the Middle East shock, while manufacturing, digital services, and exports are being supported by AI-related corporate investments and government spending on defense and infrastructure. However, downward risks to economic growth remain, as renewed energy price hikes dampen consumer sentiment.
Restrictive Financial Conditions and Discussion of Rate Hikes
The ECB Governing Council reviewed a potential rate hike during this meeting. ECB President Christine Lagarde noted in her press conference that long-term financing costs have increased significantly, with average 10-year Eurozone government bond yields rising by approximately 35 basis points since the September meeting. Corporate market-based debt financing costs reached 4.1% in August (up from 4.0% in July), and mortgage rates also climbed to 3.6%.
These self-tightening financial conditions are effectively absorbing market liquidity and curbing excessive demand. Third-quarter bank lending surveys indicate that stricter credit supply standards, driven by corporate risk aversion, along with the burden of high interest rates, have significantly reduced loan demand from both businesses and households. Given that these market-driven restrictive conditions are mitigating upward inflationary pressure, the Council unanimously reached the decision to maintain the current rate levels.
Reduction of Asset Purchase Programs (APP/PEPP) and Data-Dependent Outlook
The ECB continues to implement its balance sheet reduction policy as planned. By discontinuing the reinvestment of principal payments from maturing securities under the Asset Purchase Programme (APP) and the Pandemic Emergency Purchase Programme (PEPP), the total size of its assets is decreasing at a predictable pace. The Bank also maintains readiness to deploy the Transmission Protection Instrument (TPI) to prevent any disproportionate widening of government bond spreads among Eurozone member states.
Moving forward, the ECB will continue its “meeting-by-meeting and data-dependent” approach to monetary policy rather than pre-committing to a specific interest rate path. President Lagarde indicated that the December meeting will benefit from new economic and inflation projections, third-quarter GDP data, and further inflation updates. Future rate adjustments will be determined based on incoming economic data, the evolution of underlying inflation, and the strength of monetary policy transmission. This summary is based on the official policy statement and press conference provided by the European Central Bank (ECB) on October 29, 2026.
Official Source: Monetary policy decisions
Official Source: Christine Lagarde, Boris Vujčić: Monetary policy statement (with Q&A)